The driver was offline
The personal auto policy is often the starting point. Coverage still depends on its terms, vehicle use and the facts. A policy exclusion may need review.
Uber & Lyft accidents
If you were hurt in an Uber or Lyft crash in Miami-Dade, call my office for a free case review. If you were a passenger, we’ll go over which receipts and app screenshots to save. If an Uber or Lyft driver hit you, we’ll discuss what details can help trace the trip.
If I take your case, I’ll look for records showing whether the driver was offline, waiting for a request, or had accepted a ride. The driver’s app status at the time of the crash can affect which insurance applies. I’ll review the policies and handle communications with the insurers.
Case reviews are available in English and Spanish.

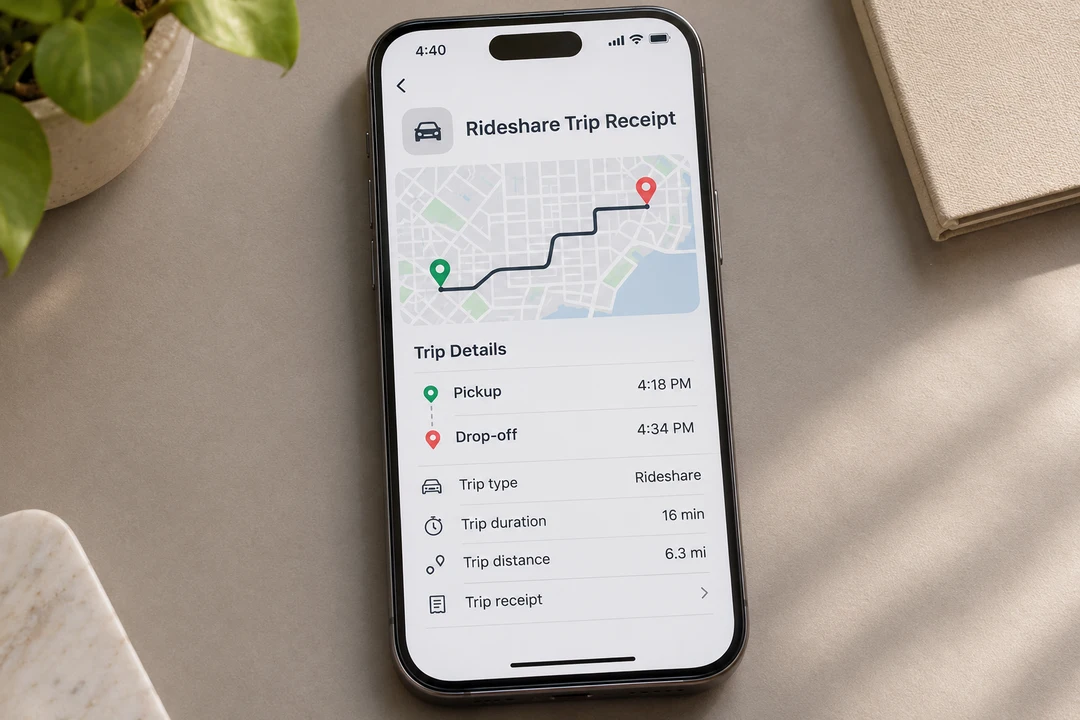
Get needed medical care and report the crash to the proper authorities when required. If it is safe, take photos and get witness details. Use the platform's reporting feature to give facts you know. Do not guess about fault or the extent of an injury.
Save the digital ride as well as the crash evidence:
Do not assume the app will keep everything for you. The steps after an accident guide explains other records to keep.
Florida's rideshare law distinguishes periods of app activity. The actual records can show which period applied at the moment of impact.
The personal auto policy is often the starting point. Coverage still depends on its terms, vehicle use and the facts. A policy exclusion may need review.
For this waiting period, Florida requires primary liability coverage. This is the first layer of insurance for covered claims against the driver. The minimum limits are:
The policy may be held by the driver, vehicle owner or platform, or the requirement may be met through a combination. The firm checks the policies and the driver's actual status.
The accepted-ride period requires at least $1 million in primary liability coverage for death, bodily injury and property damage. It begins when the driver accepts the request, before the passenger gets in. The statutory ride period ends when the last passenger has exited the vehicle. Trip records help establish those times.
These are required insurance limits, not amounts owed to each injured person. They do not decide fault or promise a payment. The actual coverage and claim must still be proved. Passenger rideshare rules should not be assumed to govern every food or package delivery trip.
The claim may involve your driver, another driver or both. Even when you had no role in driving, insurers may disagree about who caused the crash and which policy applies.
Save the trip record and the names of both drivers. The firm reviews the crash evidence, your injuries and the available policies. It can also assess requests from different insurers so the coverage questions are addressed together.
App status may still matter if you were in another car, on a bike, on a motorcycle or walking. You may not have access to the driver's app. Other evidence and formal requests may be needed to establish the status.
The collision still needs its own proof. Video, witnesses, road marks and vehicle damage can help show what happened. The pedestrian and bicycle injury page addresses visibility and road evidence for people outside a car.
Save any trip or ride request details. Note whether you were offline, waiting for a request or had already accepted a ride. Keep messages from the platform and your insurer. Those records can help identify which policies to review.
The review may include the rideshare driver's personal policy, coverage tied to the platform and the other driver's policy. Your own insurance or a household policy may also matter.
PIP medical benefits and uninsured or underinsured motorist coverage have separate conditions. Neither should be assumed from the existence of a rideshare trip. The PIP guide and UM coverage guide explain those questions.
A supported claim may address medical bills, future care, lost pay and a reduced ability to work. Pain, disability and other damages depend on the injury and the law. The evidence must link the crash to the losses.
The platform's involvement does not make the company automatically liable. The driver's role, the conduct of each party and the governing rules need separate review. If more than one person contributed to the crash, fault may also affect recovery.
First, learn which claims and parties the release covers. The offer may arrive before your care needs or all policies are known. A final release can give up rights you still need to assess.
Your own insurer may require cooperation under the policy. Requests from another insurer may raise different issues. The guide to insurance calls explains what to ask before a recorded statement or broad release.
Prompt review can help identify records before they are lost. Legal deadlines also need to be checked from the facts.
Request a free case review or call (305) 793-8687. Free consultations. No fees or costs if there is no recovery, under the signed fee agreement.
The firm may handle a matter directly, with co-counsel or through referral. Sending the form does not, by itself, mean the firm has accepted your case. Confirm acceptance and which deadlines the firm will handle. The contingency fee terms must be in writing. Do not send private medical records through the general contact form.
Rideshare definitions and insurance, § 627.748; UM coverage, § 627.727. Policy terms, app records and the facts control each review.
Clear fee policy
Personal injury matters are handled on a contingency-fee basis. Attorney’s fees and reimbursement of advanced case costs are paid only from a recovery obtained through settlement or verdict, as provided in the written fee agreement.